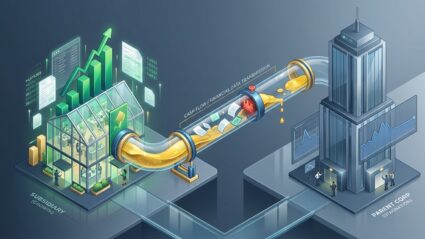
NEWInvestingA conceptual 3D visual metaphor for financial accounting disconnects in corporate business, designed in a sleek editorial illustration style. On the left side, a thriving miniature subsidiary building blooms with dynamic rising green bar charts and floating financial ledgers displaying glowing numbers. A clear, futuristic glass pipeline connects this subsidiary to a modern parent company headquarters on the right. Floating paper ledgers and digital numbers travel through the pipe, but the actual liquid golden cash within the pipe is blocked halfway, leaving the parent company side completely dry. Beside the parent company, a stock line chart remains strictly flat and stagnant. Clean studio lighting, a sophisticated color palette of corporate deep slate blue contrast with vibrant gold and emerald green accents, high-detail isometric visual presentation.

지분법 손익 늘었는데 모회사 주가가 제자리인 이유

지분법 손익은 자회사 순이익 중 모회사 지분율만큼 장부에 반영되지만 영업외손익으로 분류되며 현금 유입을 동반하지 않는다. 자회사가 배당을 실시하지 않고 이익을 유보하면 모회사 현금흐름과 배당 여력은 변하지 않는다. 여기에 중복 상장 할인과 일회성 이익 착시까지 겹치면 자회사 호실적에도 모회사 주가는 정체될 수 있다.